

Hi Multis
When I published my previous Hims & Hers (HIMS) article on October 20, I told you Q3 would come on November 9.
In the three weeks in between, quite a bit happened: Hims launched testosterone injections and a testosterone pill, Eli Lilly started selling its GLP-1 pills and injections through Hims & Hers, the famous health influencer Andrew Huberman, Ph.D., neuroscientist and Stanford professor, joined the board and the first peptides got a launch date. Things are happening fast at this company.
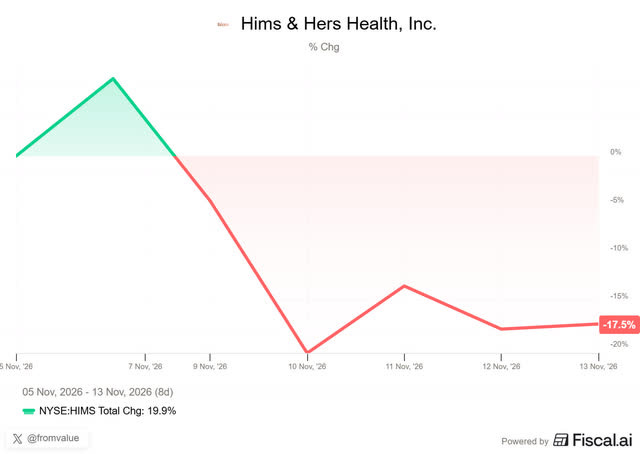
And the stock? It did what this stock does so often: jump around like an ADHD kid on a sugar high. It closed at $26 on Friday, the day of the Eli Lilly announcement, on Monday, it fell 11.8% to $22.94 before the results were out, without a clear reason and on Tuesday, after the results, it fell another 16.6% to $19.13. That’s a 26% difference in two trading days and 34.5% below the $29.21 at which I published my Q2 analysis three weeks ago.
Get a 15% discount for Fiscal AI here
To be honest, I’m very curious as I write this intro. Before this article, I had not listened to the call yet and had not looked any deeper than the results without any context. So, here we go.
The Numbers
Revenue: $890M, up 49% YoY, and exactly at the midpoint of the $880-900M guidance, but $2.9M or 0.3% below the $892.9M consensus. That’s without $18M in weight-loss membership payments Hims & Hers received in Q3 but can only count as revenue in Q4. With it, revenue would have been $908M, a clear beat of the consensus. That shows how arbitrary this sometimes is.
US revenue: $657M, up 21% YoY, after +16% in Q2 and -8% in Q1.
International: $233M, up 321% YoY; $135M of that came from Eucalyptus.
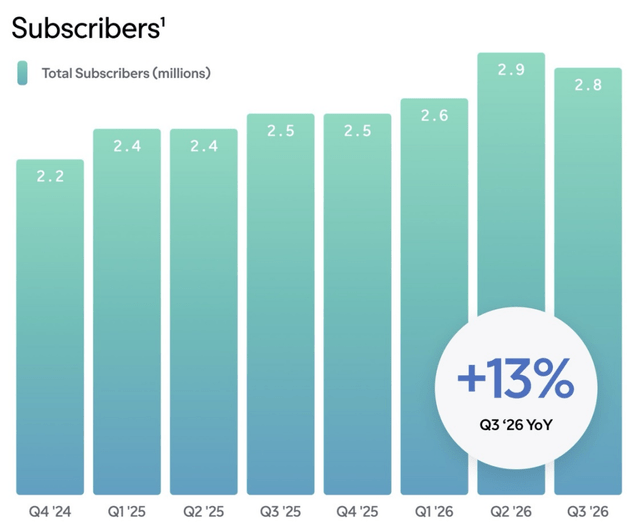
Subscribers: 2.79M, up 13% YoY, but about 100,000 fewer than in Q2. The market didn’t like this.
Monthly ARPU: $105, up from $81 a year ago.
Gross margin: 57%, down from 74% a year ago and 64% in Q2.
Adjusted EBITDA: $82M, a 9% margin, up from $78M (13%) a year ago and $60M (8%) in Q2.
GAAP net income: -$33M, versus +$15.8M last year. EPS of -$0.14 versus +$0.06 to +$0.08 expected, depending on the source. A miss.
Free cash flow: +$26M, after -$68M in Q2.
Guidance Q4: revenue $875-895M, +42% to +45% YoY, but below the consensus of about $953M. Adjusted EBITDA guidance of $70-90M.
Guidance FY2026: $3.13-3.15B, a tighter range than the previous $3.1-3.3B; adjusted EBITDA lowered to $257-277M (from $275-325M), below the consensus of about $294M.
2030 target: confirmation of the goal of $6.5B+ revenue and $1.3B+ adjusted EBITDA
Revenue growth went from 4% in Q1 to 38% in Q2 and 49% now, and the adjusted EBITDA margin improved for the second quarter in a row. But the market looked at the subscriber drop and the weak Q4 guidance. Let’s look at some more details.
At the end of March, Hims & Hers launched a weight-loss membership in the US. You need an active membership to get your medication, and most memberships renew monthly. Part of that money comes in during the quarter but only counts as revenue later, a bit like deferred revenue at a software company. In Q3, that was $18M.
In my previous article, I estimated that the first full quarter of Eucalyptus would add $75-80M on top of the roughly $40M in June. It added $95M, so really strong.
If we strip out Eucalyptus to get a better view of the core business, we see 26% YoY growth and 6% QoQ, still strong. If you add the deferred revenue, that would have been 8% QoQ. If we look at it from the other side, international without Eucalyptus grew nearly 80%, also very strong.
US growth came in at 21%, or about 24% adjusted for the deferred revenue. Hers was about 45% of US revenue, up from about 40% a year ago. Management had a target of $1B for Hers in 2026 and with $296M this quarter, that target looks very reachable.
Even if you wouldn’t think so from the press coverage of Hims & Hers, the majority of US revenue still came from non-GLP-1 offerings. For a long time, I have been saying that this is not a GLP-1 company for me and I’ll keep repeating that until people understand. Which is probably years out, haha.
The 100K Subscriber Drop
Subscribers dropping by about 100,000 doesn’t look good, does it? But there are two reasons that make sense.
Below:
What really happened to those 100,000 subscribers
What the Andrew Huberman deal means for Hims & Hers.
Peptides on Hims& Hers
The strong AI number that tackles the biggest problem in healthcare
The updated Quality Score, the valuation and my verdict.
Don’t want to miss this and other valuable information?