

Hi Multis
Hims & Hers (HIMS) reports its Q3 results on November 9. Before that, I want to go over Q2 and everything that happened since August 10, when they reported their Q2 numbers. The reason is not just that you will be well-prepared for the Q3 numbers, but also because a lot happened: an FTC lawsuit, the CEO on CNBC, penalties from Visa, the launch of both the Hims and the Hers brand in Australia and the potential legalization of peptides.
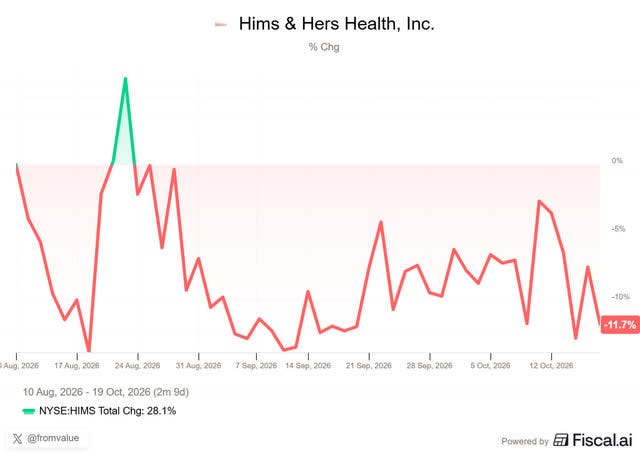
The stock is still extremely volatile. It dropped after the earnings but then, on August 19, it jumped 13.5% after founder and CEO Andrew Dudum gave an interview on CNBC. Then it dropped again but shot up on October 15, on the news that peptides may be legalized. Meanwhile, it remains one of the most shorted stocks. Consistently, more than a quarter of the float is sold short. That’s one reason for the high volatility. Today, the stock closed at $29.21, 22.5% higher than when I published my previous earnings analysis ($23.85) and I gave it a 9/10 Valuation Score. So, what is it now? Is the stock attractive right now? We will find out at the end of this article.
Let’s find out what happened.
The Numbers
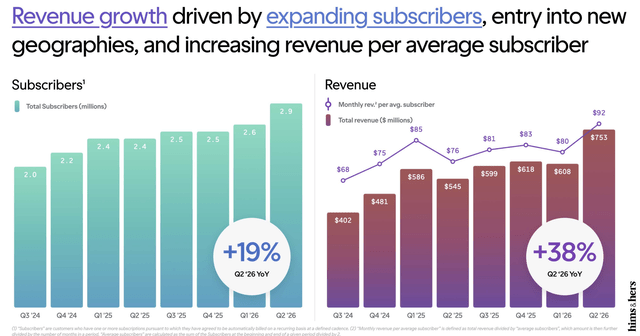
Revenue: $753M, up 38% YoY, beating the conservative guidance of $680-700M and beating the consensus of $730M by $23M or 3.15%. Very strong.
US revenue: $622M, up 16% YoY.
International: $131M, up 17x or 1,700% YoY.
Subscribers: 2.89M, up 19% YoY, more than 300K added in Q2.
Monthly ARPU: $92, up from $76 a year ago. (ARPU = average revenue per user)
Gross margin: 64%, down from 76%. More about this later, obviously.
Adjusted EBITDA: $60M, an 8% margin, down from $82M and 15% in Q2 2025, but up from $44M and 7% in Q1.
GAAP net income: -$86M, versus +$42.5M last year. EPS of -$0.37 versus -$0.05 expected. In other words, a miss and that’s what the market probably reacted to.
Free cash flow: -$68M
Guidance Q3: revenue $880-900M (+47% to 50% YoY), adjusted EBITDA $75-95M.
Guidance
FY2026: revenue raised to $3.1-3.3B (from $2.8-3.0B), adjusted EBITDA lowered at the top to $275-325M (from $275-350M).
2030 target: reaffirmed $6.5B+ revenue and $1.3B+ adjusted EBITDA.
I’m happy to see these numbers. Don’t forget, in Q1 revenue growth was just 4%. 38% is a totally different world. Subscriber growth also doubled.
From the Q2 slide deck, through Fiscal
The market focused on other things: the gross margin dropped, the top of the EBITDA guidance came down and free cash flow turned negative. That’s why the stock fell after earnings. But as always, context matters.
In my Q1 article, I told you the acceleration would come and it came, even more than management expected. The stock is up 22.5% since that analysis. That’s what you get as a Multi: the analysis before the market figures it out.
Below this line: more than 4,750 words of analysis you won’t find anywhere else.
With a full analysis, a clear catalyst for 2027, the Selling Rules, the updated Quality Score and the valuation, including a reverse DCF (next to the correct ratios to look at). And my clear answer: buy, hold or sell before the Q3 earnings on November 9.
That’s 19 days from now. Free readers will know what I think after the stock moves. Paying Multis know now.
Don’t want to miss it anymore?