

Hi Multis
On October 20, 2017, founder and CEO Forrest Li stood on the NYSE podium, waiting to ring the bell for Sea’s IPO.
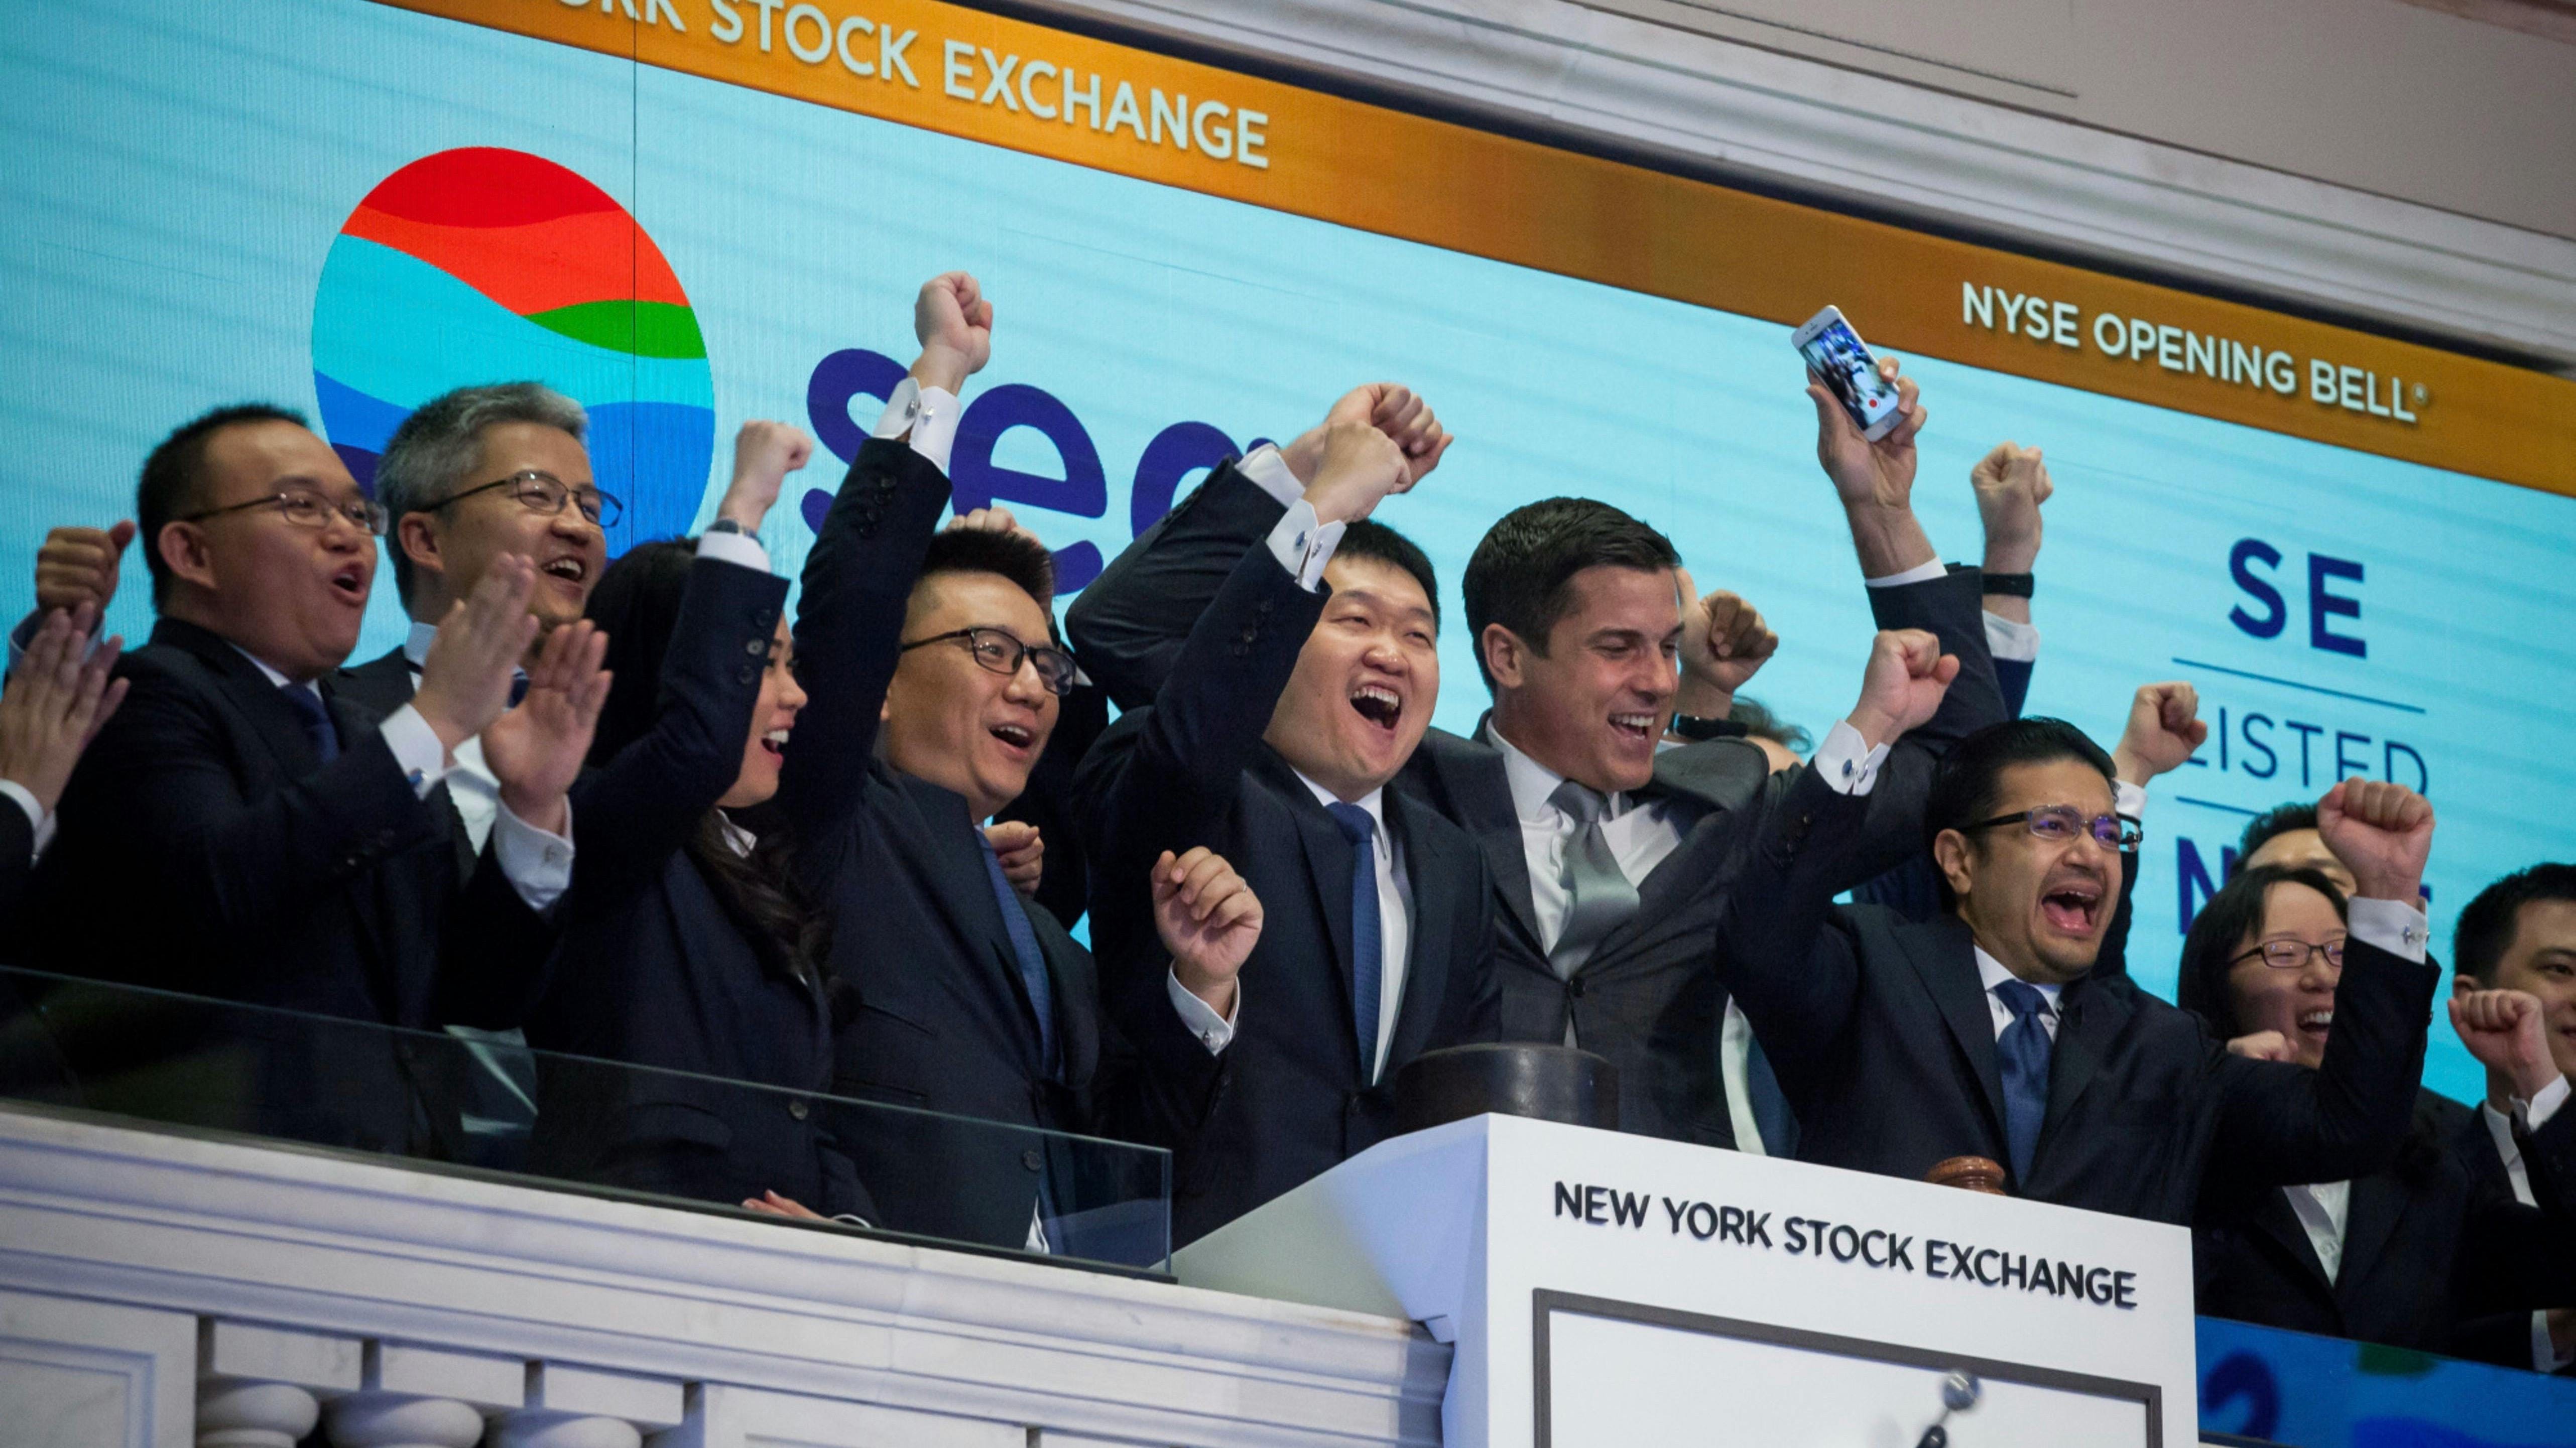
Last week, exactly 9 years later, he sent his employees a memo that raised eyebrows in investing circles. The memo announced two key changes: Sea will sell its in-house cloud to other companies, and Monee, its fintech arm, could one day go public on its own. The stock dropped 9.1% that day to $80.43, and it has since fallen to $74.73 right now.
Since that jump on August 11, after the earnings, the stock has dropped 35.5%.
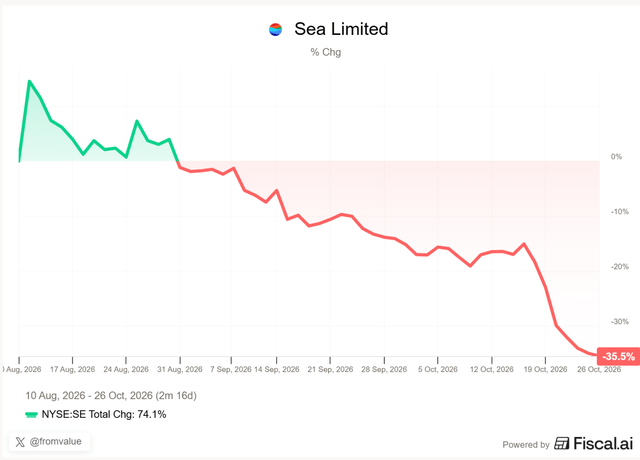
As you can see, the drop had already started before the announcement of this week. So, what has happened? Let’s first analyze the Q2 results, then the memo (on which I will share my opinion), and then look at the Quality Score and valuation to decide whether Sea (SE) is a BUY now.
Sea Limited Group Results
Let’s start with the group results, then focus on the company’s different arms.
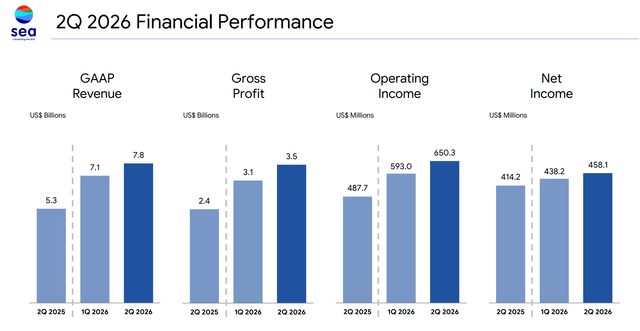
Revenue came in at $7.79B, up 48.1% YoY and almost 10% above expectations. That’s exceptionally strong. Growth even accelerated after that strong 47% revenue growth in Q1.
Gross profit grew 47.3% to $3.55B, for a gross margin of 45.6%. That’s also great. Higher revenue resulted in similar growth in gross profit.
Operating income rose 33.3% to $650M.
Net income rose 10.6% to $458M, or $0.70 per diluted share, while analysts expected $0.83 to $0.86. That looks bad, but most of it comes from taxes. Income tax expense jumped 74% to $251M, with an effective tax rate of 35%, up from 25% a year ago. At last year’s rate, EPS would have been about $0.11 higher, so around $0.81.
The rest of the miss comes from Monee’s higher loss provisions and lower interest income. If you remember from NU or MELI, if a bank or fintech lends out money, it has to provide provisions for losses. If the loan book grows more than analysts expected, it means that the loss provisions are higher, and that eats into profitability. That’s accounting, and it’s also weird to see a company being punished for growing faster than expected.
All in all, strong results. This is an overview from the earnings slide deck.
Slide deck via Fiscal AI. Wanna try it? With this link, you get a 15% discount.
Stock-based compensation fell 18.5% to $132M, while Sea bought back 4.7M shares for $416.8M, more than 2.5 times as many as in Q1, at an average price of about $89. Buying more when the stock is cheaper is exactly what you want. Of course, the stock has dropped more, but you can’t easily foresee that. I don’t think Forrest Li let the stock drop on purpose to buy more shares, haha.
Guidance: Sea kept its target of around 25% GMV growth for 2026 (GMV = gross merchandise volume, the value of all goods sold on Shopee), though currency fluctuations could have some negative impact. Forrest Li is now “optimistic that Shopee will achieve the milestone of US$1 billion in adjusted EBITDA for the full year.“ Great.
Let’s go to the different branches.
The market has made up its mind about the memo. I took my time to think it through and came to my own conclusion.
Below: what a Monee IPO would mean for us as shareholders, my take on Sea Cloud, the accounting change that will confuse many investors next quarter, what Shopee’s Brazil numbers mean for Mercado Libre shareholders, the updated Quality Score, the full valuation and what I did with my own position this week.
Don’t want to miss this valuable information anymore?