

Hi Multis
Last week, on Thursday, November 12, Nu Holdings (NU) released its earnings.
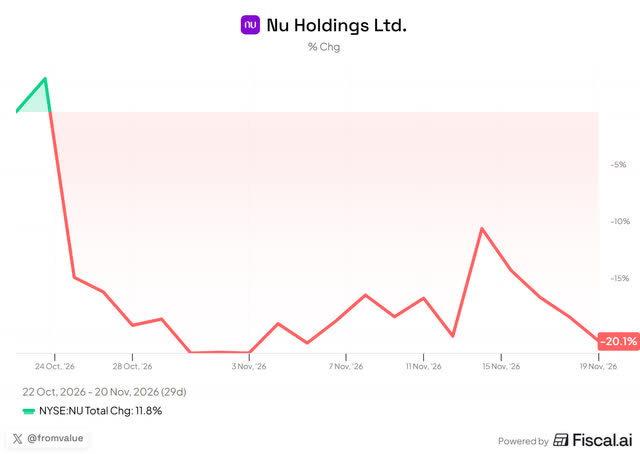
Since the Brazilian elections on October 25, the stock has been very volatile. It dropped by more than 20% then, won back about half of that loss after the earnings but then slid down again. It’s now down 20% since the elections.
So, let’s look at the earnings in detail. After that, of course, as always, the Selling Rules, the Quality Score, the Valuation and my Buy-Hold-Sell rating.
First, the numbers.
The Numbers
(FXN = FX-neutral, the growth without currency effects)
Revenue: $6.26B, +37% YoY FXN, +8% QoQ, beating the consensus by about $300M
EPS: $0.22, in line with the consensus or a small miss of less than a cent, depending on the consensus you check.
Net income: $1.09B, +31% YoY FXN, +5% QoQ. A new record, one quarter after the first billion-dollar quarter in Nu’s history.
Gross profit: $2.60B, +35% YoY FXN, +8% QoQ.
Customers: 142.6M, +12% YoY, 3.7 million net adds in the quarter.
Activity rate (monthly active customers divided by total customers; a customer is active if they generated revenue for Nu in the last 30 days): 83.6%, and a record 86.3% in Brazil.
ARPAC (Average Revenue Per Active Customer): $17.7 per month, +21% YoY FXN.
Cost to serve: $1.1 per active customer per month, +10% YoY FXN.
Credit portfolio: $41.6B, +33% YoY FXN, +6% QoQ.
Deposits: $47.5B, +19% YoY FXN, +5% QoQ.
NIM (net interest margin): 22.5%, from 22.9% in Q2.
Risk-adjusted NIM: 12.1%, from 12.4% in Q2 and 10.8% a year ago. Excluding one-offs, 12.7%, up from 11.9%.
Efficiency ratio (operating expenses divided by net revenue, so lower is better): 19.3%, from 19.5% in Q2 and 20.3% a year ago. So, Nu spends $19.3 to earn $100 in net revenue.
ROE (return on equity): 32%, down from 33% in Q2.
NPL 15-90 (loans 15 to 90 days late): 4.86%, from 4.83% in Q2.
NPL 90+: 7.3%, from 6.9% in Q2 and 6.7% a year ago.
This slide shows you the incredible evolution of the last four years at NU.
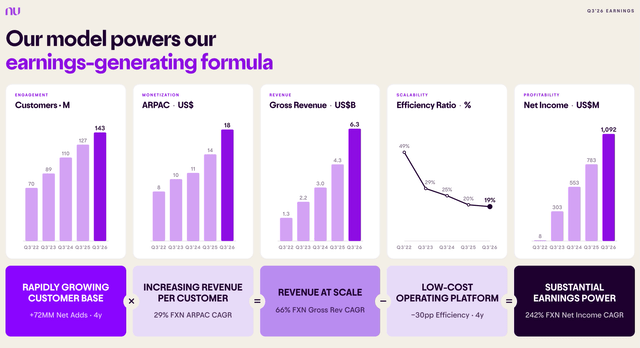
In Q3 2022, Nu earned $8M. In Q3 2026, that was $1,092M. That’s x137, crazy. In the same period, the number of customers more than doubled from 70 million to 143 million, ARPAC more than doubled from $8 to $18 and the efficiency ratio went from 49% to 19%. Very, very impressive. Over the same 4-year period, the stock is up only 49%.
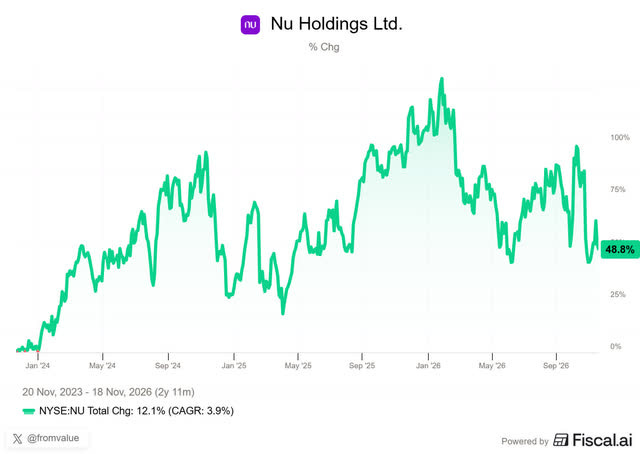
Profits grew by 13,700% in four years and the stock is only up 49%. That gap has to close one day, in one direction or the other.
Below:
The one-off that makes the margins look weaker than they are
The new Mexican law that could be a strong tailwind for NU.
The first signs from the US launch.
The updated Quality Score,
My unique systems of valuating a stock that is hard to value.
Don’t want to miss it?