

Hi Multis
Earlier this week, on Wednesday, November 4, after the market close, to be precise, Mercado Libre (MELI) published its Q3 2026 results.
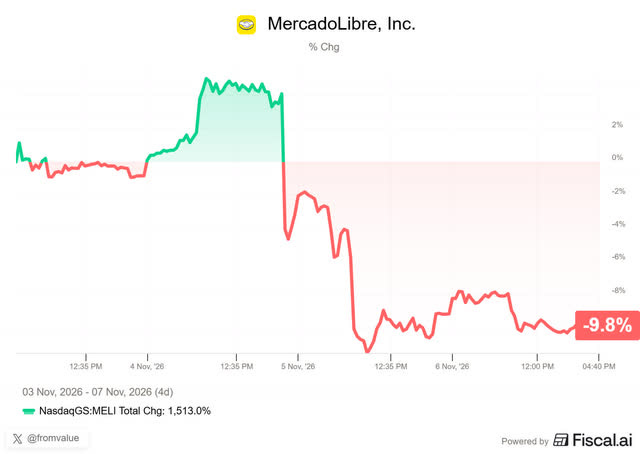
The stock dropped by 13% initially and while it recovered a bit, it’s still down almost 10%.
I could hear the collective sigh of many Multis all the way to Belgium and Flo even made this joking post in our community.
And I feel like investors are going after Mercado Libre's stock with pitchforks and torches as well, haha.
Many also point at the 5-year chart.
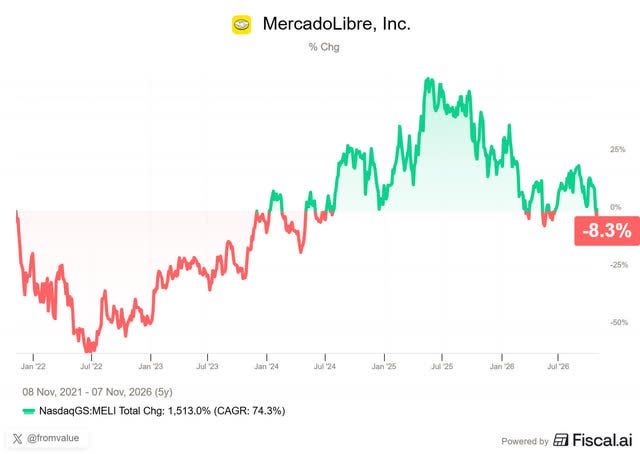
One Multi sent me a message: “I have my doubts about MELI. The markets can’t be wrong for that long, can they?”
Well, whether you like that or not, they can.
First, 5 years ago, we were at the peak of the COVID bubble. I’m pretty sure these people will not look at the 4-year return.
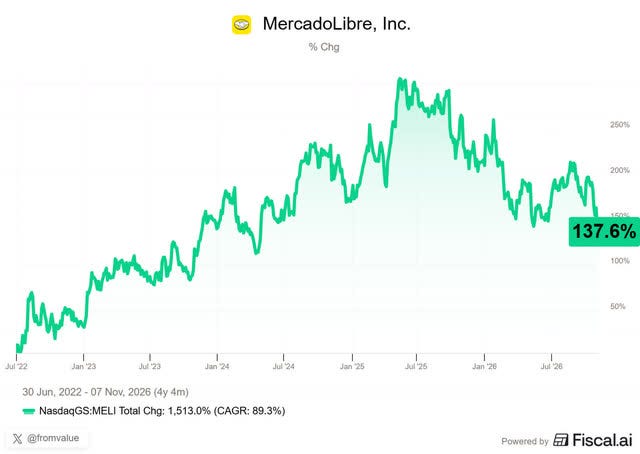
Sure, you can say I’m cherry-picking because this starts at the bottom of the 2022 bust. But if you start 5 years ago, you cherry-pick as well, but negatively then. Why 5 years and not 4? Or why not 10 years?
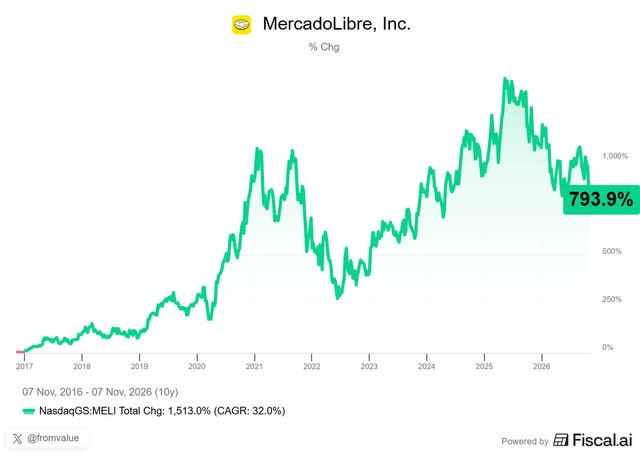
As you can see, Mercado Libre is still a 9-bagger over that period, despite the big recent drop. I would sign for that for the next 10 years.
Oh, and maybe you should look at the chart of this loser stock from 2007 tot 2015, 8 long years. What a POS, right? Who would want to have that stinker?
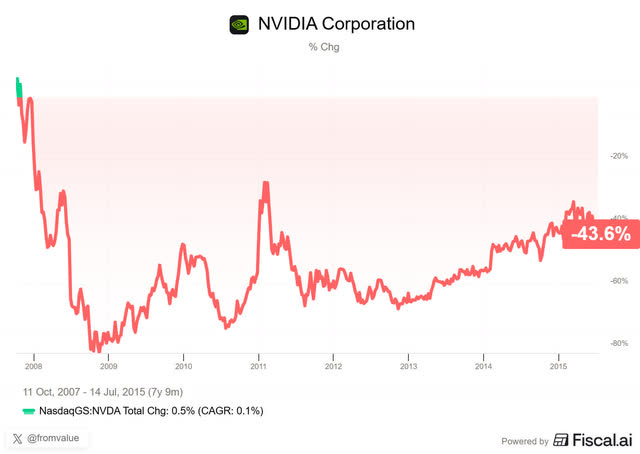
The markets can be irrational for a very, very long time. But 10 years? No. Then the fundamentals matter. Over 5 years, mostly as well, but it depends more on the starting point than on an exception.
But enough about the stock price. Let’s focus on what really matters: the fundamentals.
The Numbers
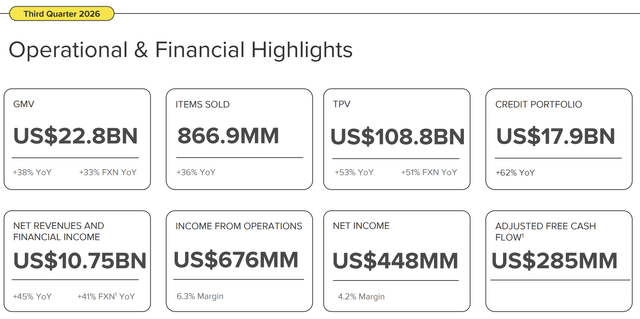
Revenue: $10.75B, +45% YoY in USD and +41% FX-neutral. Growth has now stayed above 30% for 31 quarters in a row. Mercado Libre is the only company in the world (out of 83,000 public companies) that can say this. Revenue was basically in line with consensus (a slight beat of 0.37%), which may have disappointed investors who are used to big revenue beats from MELI.
EPS: $8.83, +6% YoY, missing the consensus by 4.75%.
Net income: $448M, +6% YoY, resulting in a net income margin of 4.2%..
Operating income: $676M, -6% YoY (-4% FX-neutral), a margin of 6.3%, versus 9.8% a year ago and 6.7% in Q2
Gross margin: 40.8%, versus 43.3% a year ago and 40.9% in Q2
Let’s look at the marketplace (or “Commerce” as MELI calls it) and Mercado Pago.
Commerce:
GMV (gross merchandise value, the sum of everything sold on the platform): $22.8B, +38% in USD, +33% FX-neutral
Items sold: 867M, +36% YoY
Unique active buyers: 93.9M, +22% YoY, 17 million more than a year ago
Items sold per unique active buyer: 9.2, +12% YoY
Same- and next-day shipments: 258M, +49% YoY
Total shipments: 591M, +45% YoY
Fintech (Mercado Pago):
Monthly active users: 92.9M, +29% YoY
Assets under management: $25.1B, +67% YoY
TPV (total payment volume): $108.8B, +53% in USD, +51% FX-neutral
Credit portfolio: $17.9B, +62% YoY
Credit card portfolio: $8.5B in outstanding balances, +76% YoY, 47% of the total credit book, with a record 2.9 million cards issued
NIMAL (net interest margin after losses): 20.1%, versus 20.7% in Q2 and 21.0% a year ago
Advertising: +58% YoY in USD, +51% FX-neutral
Revenue by country:
Brazil $6.00B (+50% in USD, +41% FX-neutral)
Mexico $2.43B (+47%, +36%)
Argentina $1.82B (+26%, +42%)
Other $502M (+63%)
Here’s an overview from the earnings slide deck:
I also put together my own overview with some extra information.
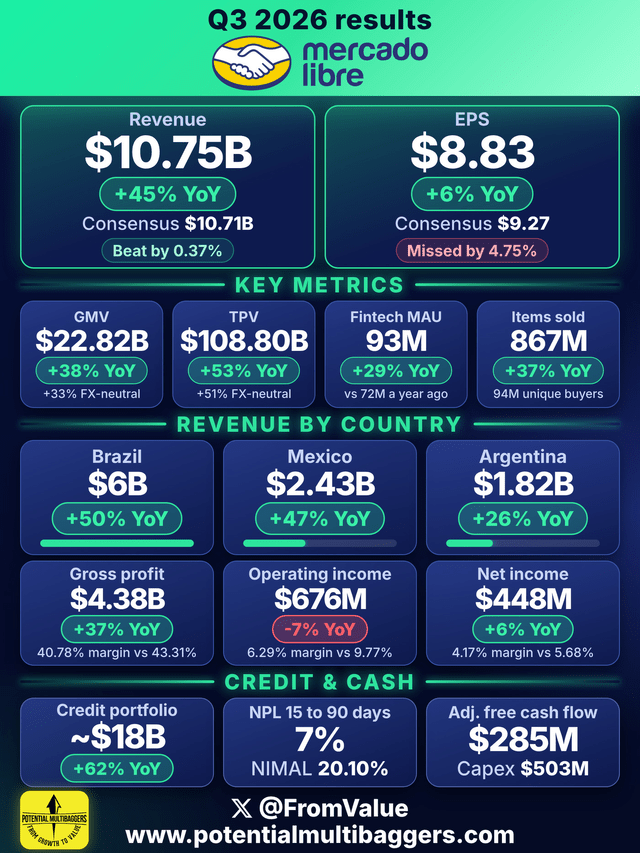
Those are the numbers, but there’s a lot to unpack about them.
Below: the real reason the margins dropped, the hidden number that shows the plan is already working and the Brazilian experiment almost everyone overlook, the scary credit number the bears point at and what it really means, my Selling Rules, the updated Quality Score, and the full valuation.
Don’t miss this premium information to make your decision.