

Hi Multis.
Global-e (GLBE) reported its Q2 2026 results on August 12. I expect Q3 earnings in a month or so. Before the earnings flood opens, I think this is a good time to review how Q2 went and what to watch for in Q3. I can already tell you you may be confused by Q3 if you don’t read this article for context.
In my Q1 article, I said that Global-e kept delivering but the stock didn’t respond to the good earnings. Well, that changed.
Just before the Q1 report in May, the stock traded around $27; when I wrote the Q1 analysis, it traded at $30.64, and I gave it a 9.5/10 Valuation Score and a STRONG BUY rating. Since then, the stock is up 35% from that day.
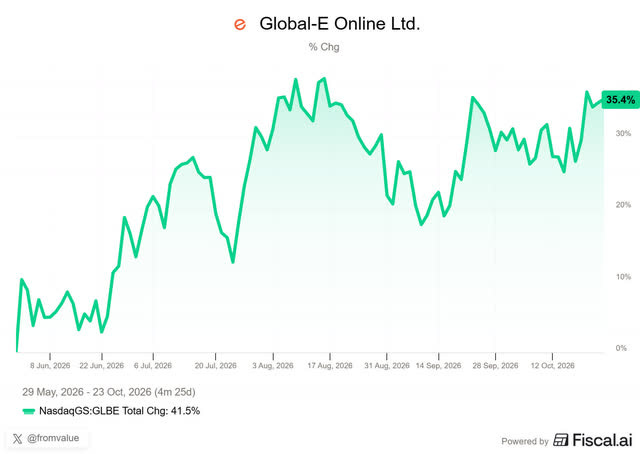
Is the stock still attractive now? Let’s find out.
If you’re new here, Global-e helps brands sell online in other countries as if they are a local shop.
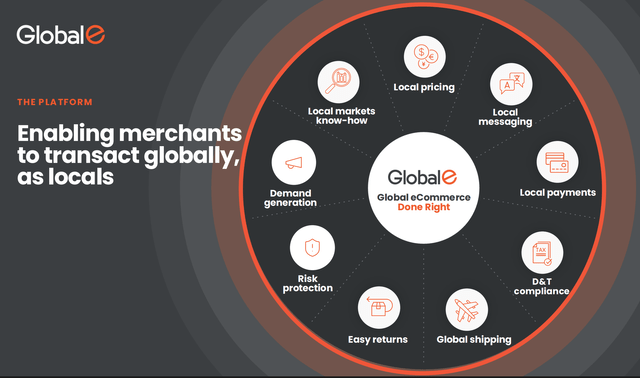
Q2 earnings slide deck, via Fiscal
The shopper in the other country sees prices in their own language and currency, uses their usual payment method, and gets the package shipped to their door. For brands, Global-e takes care of the duties, taxes, translations, shipping and returns. In other words, it takes the annoying stuff off brands’ plates and does it for them. As a result, brands sell more and become more profitable. That’s always a strong selling argument.
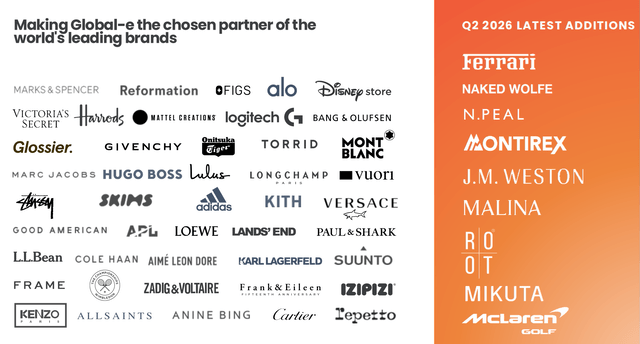
It works with big international brands. This quarter, it added Ferrari as a customer. You'll know many more of its customers.
Let’s dive into the numbers.
The Numbers
Revenue: $299M, up 39% YoY, $16M or 5.6% above the consensus. Very strong!
Non-GAAP EPS: $0.37, up from $0.22.
GAAP EPS: $0.27, up from $0.06 and $0.05 or 22.7% above expectations. So it wasn’t just revenue that was strong; earnings were, too.
GMV (Gross Merchandise Value, the total value of everything sold through the platform): $2.09B, up 44%. Again, very strong.
Gross profit: $135.4M, up 36%
45.3% gross margin versus 46.5% a year ago.
Adjusted EBITDA: $62.4M, up 62%, a 20.9% margin, vs. 17.9% last year.
GAAP net profit: $47.7M, up from $10.5M a year ago, up 354%.
Free cash flow: $73.2M, a FCF margin of 24.5%.
If you add up the revenue growth (39%) to the FCF margin (24.5%) and you get 63.5. As a reminder, the Rule of 40 says a company like this is in great shape when that sum is above 40. Management likes to have a Rule of 50, and Q2 blew that goal out of the water.
Global-e’s FCF margins are very volatile from quarter to quarter because of seasonality, so let’s take the last-twelve-months numbers for that Rule of 40 calculation as well. Then we see 31.4% revenue growth and 26.2% FCF margin, which adds up to 57.6, still an elite score.
In May, I rated Global-e a STRONG BUY at $30.64. The stock is up 35% since. The question is now: after this jump, is it still interesting to buy? The answer may surprise you.
Below: why Q3 may confuse investors (and why you shouldn’t be one of them), the metric I stop watching from now on and what I watch instead, the Shopify story that could become a major growth driver, the Selling Rule I just removed (and the ones I kept, of course, the updated Quality Score, the valuation and my verdict after the 35% run. Don’t want to miss opportunities like this anymore?