

Hi Multis
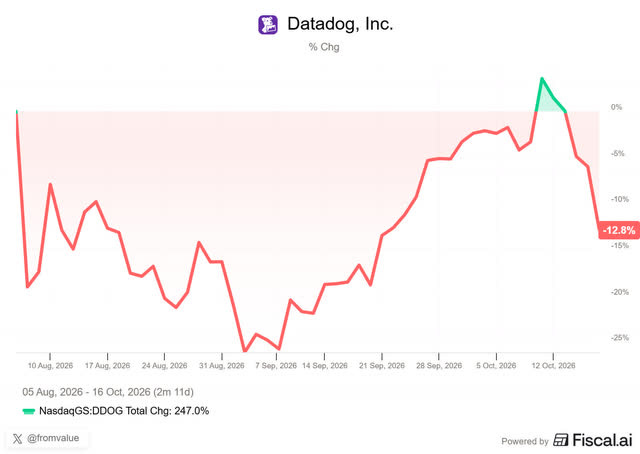
Datadog (DDOG) reported its Q2 2026 results on August 6. The stock dropped 26% in the three weeks that followed but the stock climbed back up and last week, the price was even up 3.6% from the pre-earnings level. The sell-off of the last week turned that around again and now the stock is down 12.8%.
This is another example of how fickle the market is and how volatile Potential Multibaggers can be.
So, is the stock attractive already? We will find out in this article. Let’s first take a deeper look at the earnings.
The Numbers
Datadog’s Q2 revenue came in at $1.121B, up 36% YoY. The company had guided for $1.07B to $1.08B, and analysts expected about $1.078B. So, that’s a $43M beat. Strong.
Revenue grew $115M QoQ, a record “by a significant margin,” according to CFO David Obstler. If we look at the revenue, we see that Datadog has accelerated its revenue growth considerably since Q1 2025.
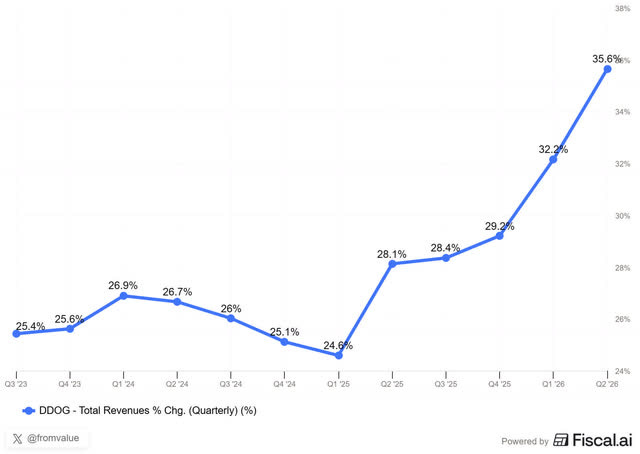
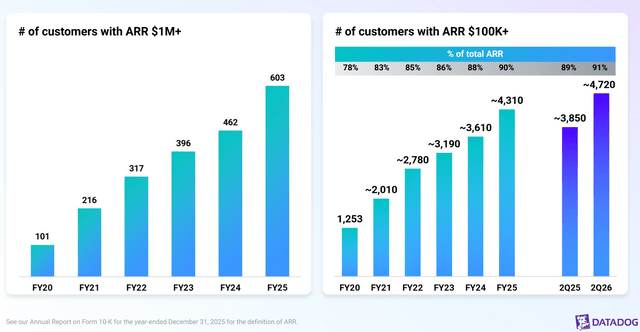
That’s exceptional for a company this mature already. The main driver isn’t new customers, but existing customers spending more. You can see that in these charts from the earnings call slides.
Non-GAAP EPS came in at $0.65, $0.07 above the consensus. The non-GAAP operating margin rose to 23%, from 20% a year ago. Free cash flow was $279M, a solid 25% margin. Very strong again.
This gives a good overview. This is not from the quarter but on a trailing-twelve-month basis.
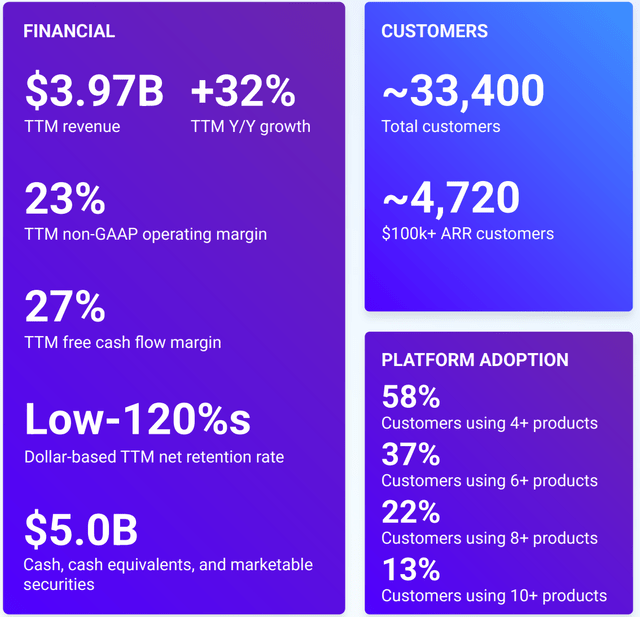
So, very strong numbers.
For a while, the big fear was that AI would make most cloud software obsolete. But Datadog’s non-AI customers, the banks, retailers, insurers and software companies are doing very well. Founder and CEO Olivier Pomel on the Q2 call:
Revenue growth for our non-AI customers also accelerated again this quarter to the high 20s percent YoY, up from the mid-20s last quarter and 18% in the year ago quarter.
From 18% to the high 20s in one year in the segment AI was supposed to annihilate.
But only looking at existing customers and ignoring new customers would be a mistake as well. New customers accounted for about 30% of revenue growth, up from 25% in Q1, and the bookings of new customers in enterprise more than doubled.
And the runway is long. Founder and CEO Olivier Pomel said at the Citi Global TMT Conference in September that Datadog has about 13% to 14% of the observability market, a market growing at 15% to 30% a year. And then Olivier Pomel said something we love to hear as Multis:
And so you do not have to have a lot of imagination to understand how we can grow 5 or 10x from that.
So, non-AI customers doing well, new customers strong, how about AI customers? Datadog now has over 750 AI customers and 31 spend more than $1M a year, up from 22 last quarter. 8 spend more than $10M, 3 more than last quarter. All of the top 10 AI leaders are Datadog customers. From Datadog’s Investor Day slides:
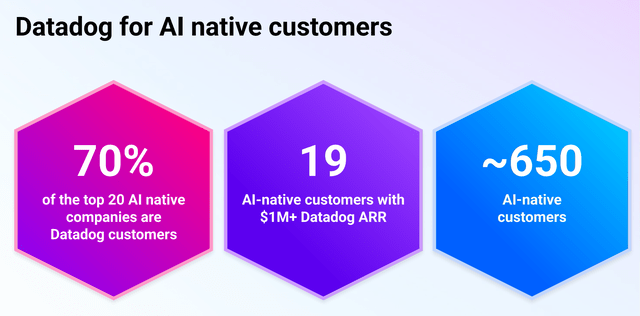
So, you can say without hesitation that Datadog is firing on all cylinders and the company is accelerating more and more.
So the business is accelerating on all fronts. And still, the stock dropped quite a bit initially, then slowly regained the lost territory and is now down again. The reason for the drop was one small detail from the earnings call.
By the way, last quarter I wrote that 2026 growth would end above 30%, when the guidance still said 25% to 27%. Guidance is now 30%.
Below: All the crucial data about Datadog you need to know, its new AI launches, an update of the Quality Score and the valuation.
Don’t want to miss it anymore?