

Hi Multis
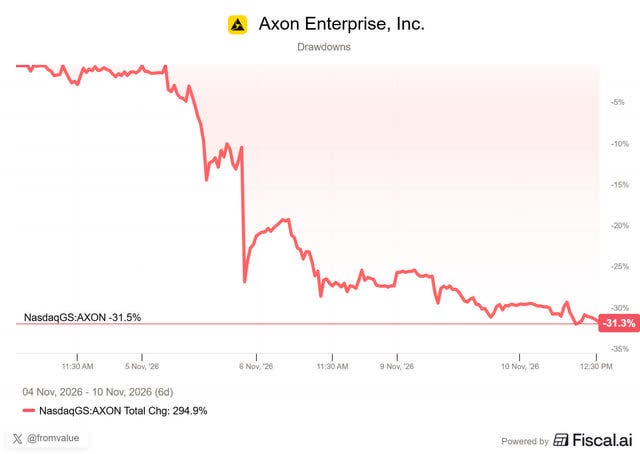
Last week, on Thursday, November 5, Axon (AXON) reported its Q3 2026 earnings and the market hated them. The stock has dropped more than 30% so far.
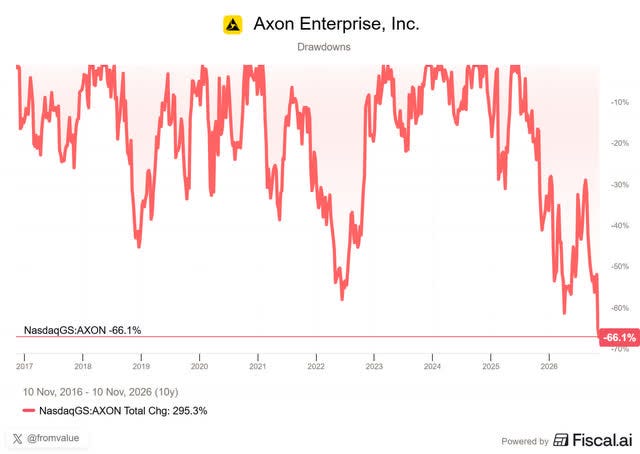
If you zoom out, you can see that it’s down 66% from its high, the biggest drop in more than a decade. The last time it dropped so much was actually in 2014.
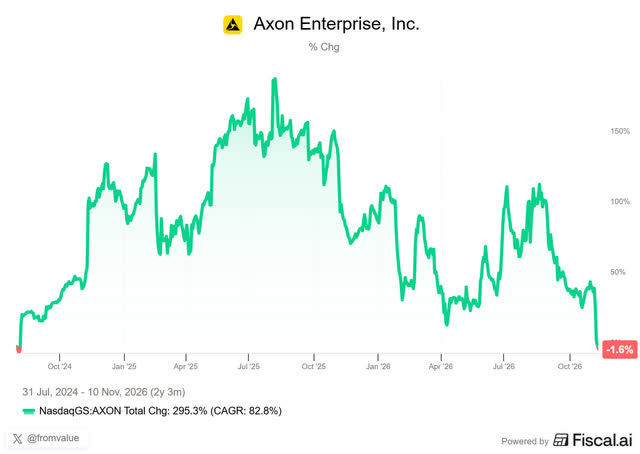
The stock is also at the lowest level since August 1, 2024.
If you believe in the efficient market theory (which I definitely don’t), then you must think the company is failing outright. But it doesn’t mean the market can’t be right, of course. Separating signal from noise, that’s what I try to do, and that’s what this article is meant for. Here we go!
The Numbers
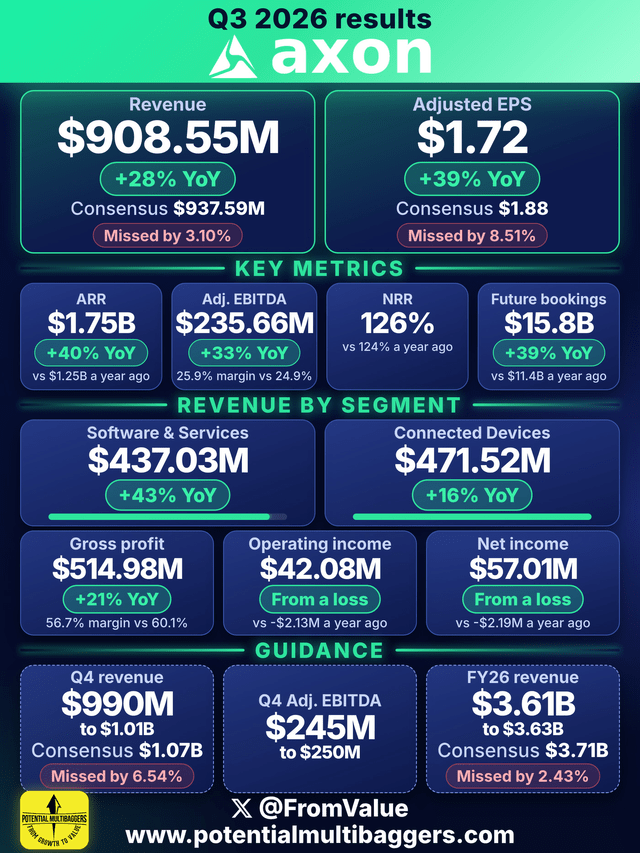
Revenue: $909M, up 28% YoY, but 3% below the consensus of $937.59M. It ends the streak of ten consecutive quarters with more than 30% growth and at least 20 quarters of beating the revenue consensus. Ouch.
Adjusted EPS: $1.72, versus $1.24 a year ago, and 8.5% below the consensus of $1.88. Not good.
Adjusted EBITDA: $236M, up 33%, a 25.9% margin. That’s better.
Adjusted gross margin: 59.2%, down from 62.7% a year ago.
Free cash flow: negative $19M, versus positive $33M a year ago.
Net revenue retention: 126%, up from 124% a year ago. Strong.
Future contracted bookings: $15.8B, up 39%. Again: very strong.
Annual recurring revenue: $1.75B, up 40%.
Software & Services revenue: $437M, up 43% YoY, an acceleration from 36% in Q2. Strong.
Connected Devices revenue: $472M, up 16%.
TASER came in at $233M (down 2%),
Personal Sensors (mostly body cameras) at $114M (up 6%) and
Platform Solutions (in-car video, fixed cameras, drones, counter-drone, VR hardware) at $125M (up 106%).
Axon lowered its full-year revenue guidance from 32-34% growth to about 30%, or $3.61B to $3.63B. The free cash flow target went down from about $450M to $350-400M.
I summarized the results in this visual.
A 30% drop sometimes means a broken company. Is that the case here as well?
Below: the reason behind the miss, my take on the biggest investment in Axon’s history, the customer group that is growing fast.
I also update my Potential Multibaggers Quality Score and look at the valution.
The stock is down 66% in total. Is this an opportunity or a warning?
Find it out below.